
Arlington is in north Snohomish County where the two forks of the Stillaguamish River meet, about thirty-five to forty minutes north of our Mill Creek office. It pairs a traditional downtown on Olympic Avenue with newer neighborhoods near Smokey Point and rural land in every direction. Choosing a home loan in Arlington comes down to four things: your down payment, your credit, your income and the property itself. Home Right Lending reviews all four with you and then shows which loan types fit, what each would cost and how the monthly payments compare.
Call Home Right Lending at (425) 642-4477 about a home loan in Arlington.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
The Cascade Industrial Center and Arlington Municipal Airport anchor local employment, and Everett is within commuting range. Outside the newer subdivisions, buyers run into acreage, wells and septic systems, and manufactured homes, and some rural addresses may be eligible for USDA financing depending on the current map. Conventional loans suit many borrowers with established credit, FHA loans allow lower down payments and more flexible credit guidelines, VA loans serve eligible veterans and service members, and USDA loans cover eligible rural addresses. Jumbo loans come in when the amount is above the conforming limit, which is set each year.
REQUEST A FREE CONSULTATION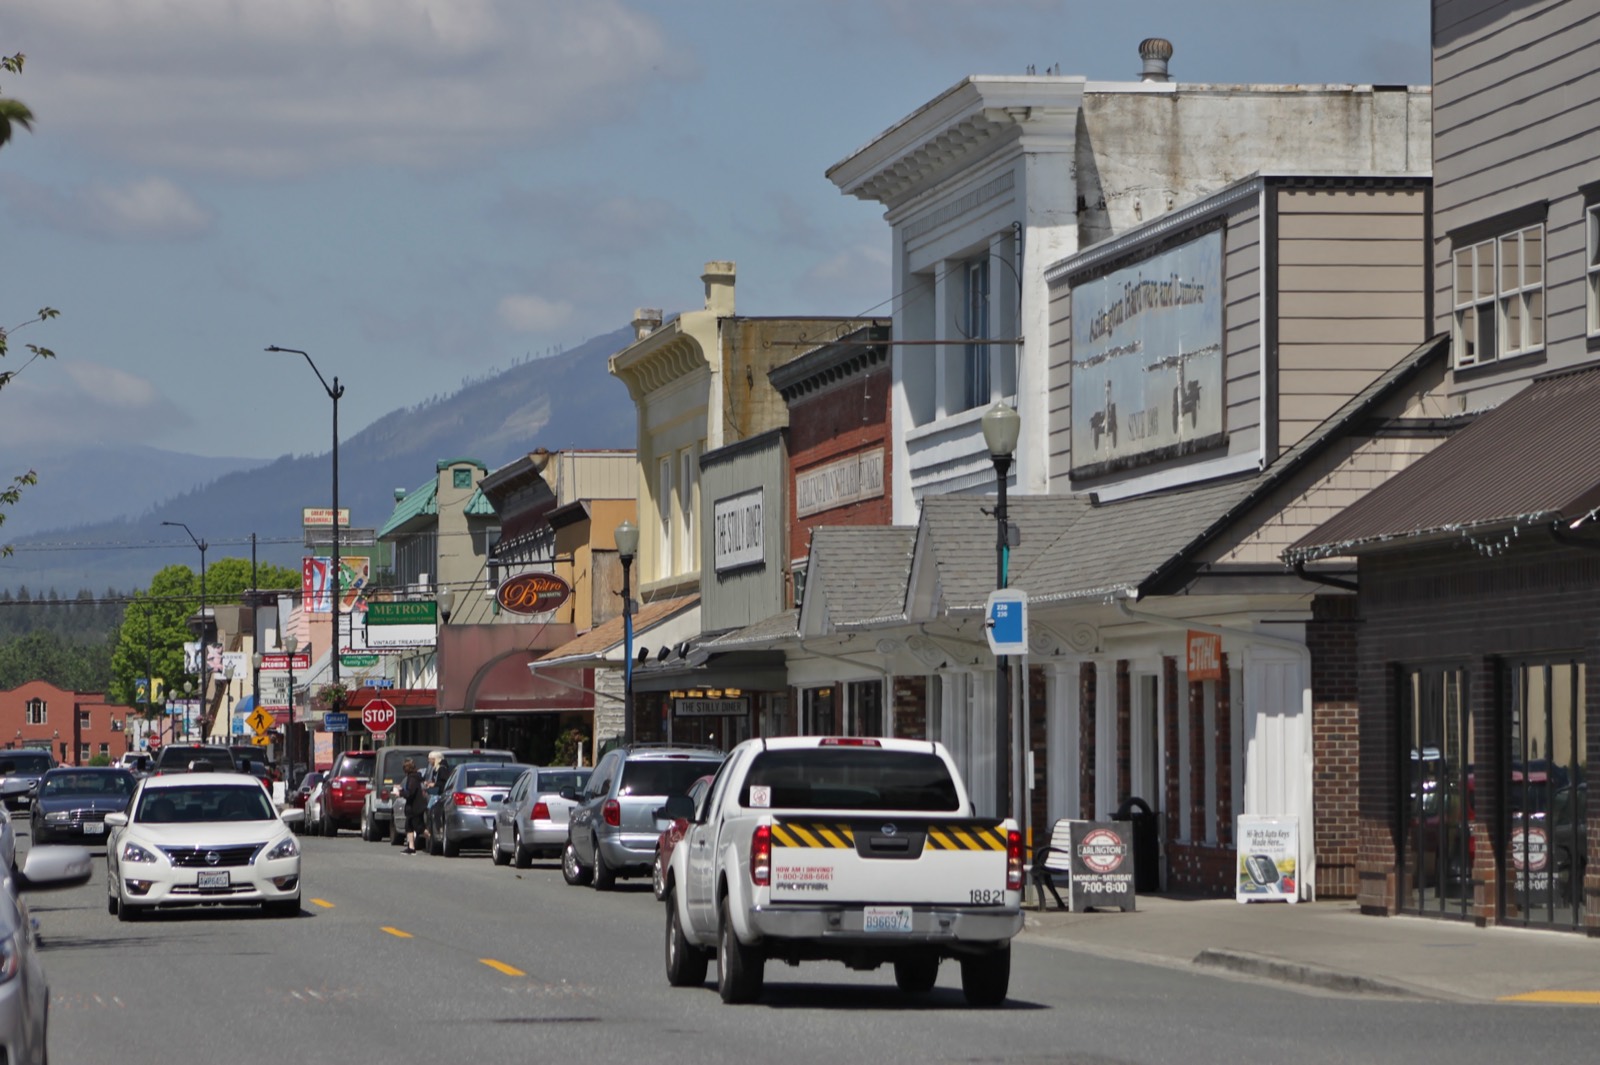
Photo: SounderBruce, CC BY-SA 4.0 (resized)
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Housing ranges from early-1900s homes in Old Town to 1990s and 2000s subdivisions such as Gleneagle and the newer neighborhoods around Smokey Point, plus farmhouses and manufactured homes on acreage. Throughout your Arlington purchase or refinance, you get straightforward updates in English or Spanish, a clear list of what is still needed and a review of your Closing Disclosure before you sign.
If you are still early in the process, we can start with a pre-approval so you know your budget before you tour homes in Arlington. It also tells sellers your financing has already been reviewed.
Home Right Lending works with borrowers throughout Arlington, including Old Town Arlington, Smokey Point, Gleneagle and Kent Prairie, and across the north Snohomish County area. Arlington is about thirty-five to forty minutes from our Mill Creek office, and most of the loan process can be handled by phone and online.
Thinking about a home loan in Arlington? Reach Home Right Lending at (425) 642-4477, apply online or use the form on this page, in English or Spanish. This is not a commitment to lend, and programs, terms and eligibility are subject to change. NMLS 2362313.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Home Loans · All loan options · Mortgage rates
Most purchase loans close in about 30 to 45 days from a signed purchase agreement. The timeline depends on the loan type, the appraisal, title work and how quickly documents are provided.
Plan on recent pay stubs, W-2s or tax returns, bank statements and a photo ID. Self-employed borrowers usually provide business and personal tax returns or, for some programs, bank statements. We give you a specific list after reviewing your situation.
Most buyers choose between conventional, FHA, VA, USDA and jumbo loans, each with fixed-rate and sometimes adjustable-rate options. Which ones you may qualify for depends on your credit, income, down payment and the property. We compare the eligible options side by side.