
Arlington is in north Snohomish County where the two forks of the Stillaguamish River meet, about thirty-five to forty minutes north of our Mill Creek office. It pairs a traditional downtown on Olympic Avenue with newer neighborhoods near Smokey Point and rural land in every direction. Most sellers and listing agents in Arlington expect a pre-approval letter with an offer. Home Right Lending is a mortgage broker in Mill Creek that can review your file, compare lenders and prepare a letter your agent can submit with confidence.
Call Home Right Lending at (425) 642-4477 about mortgage pre-approval in Arlington.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
The Cascade Industrial Center and Arlington Municipal Airport anchor local employment, and Everett is within commuting range. Outside the newer subdivisions, buyers run into acreage, wells and septic systems, and manufactured homes, and some rural addresses may be eligible for USDA financing depending on the current map. The process usually takes three steps: you apply online or by phone, you send income and asset documents, and we review everything and discuss the results with you. If something in the file needs attention, such as a credit item or a gap in documentation, you learn about it before you are under contract.
REQUEST A FREE CONSULTATION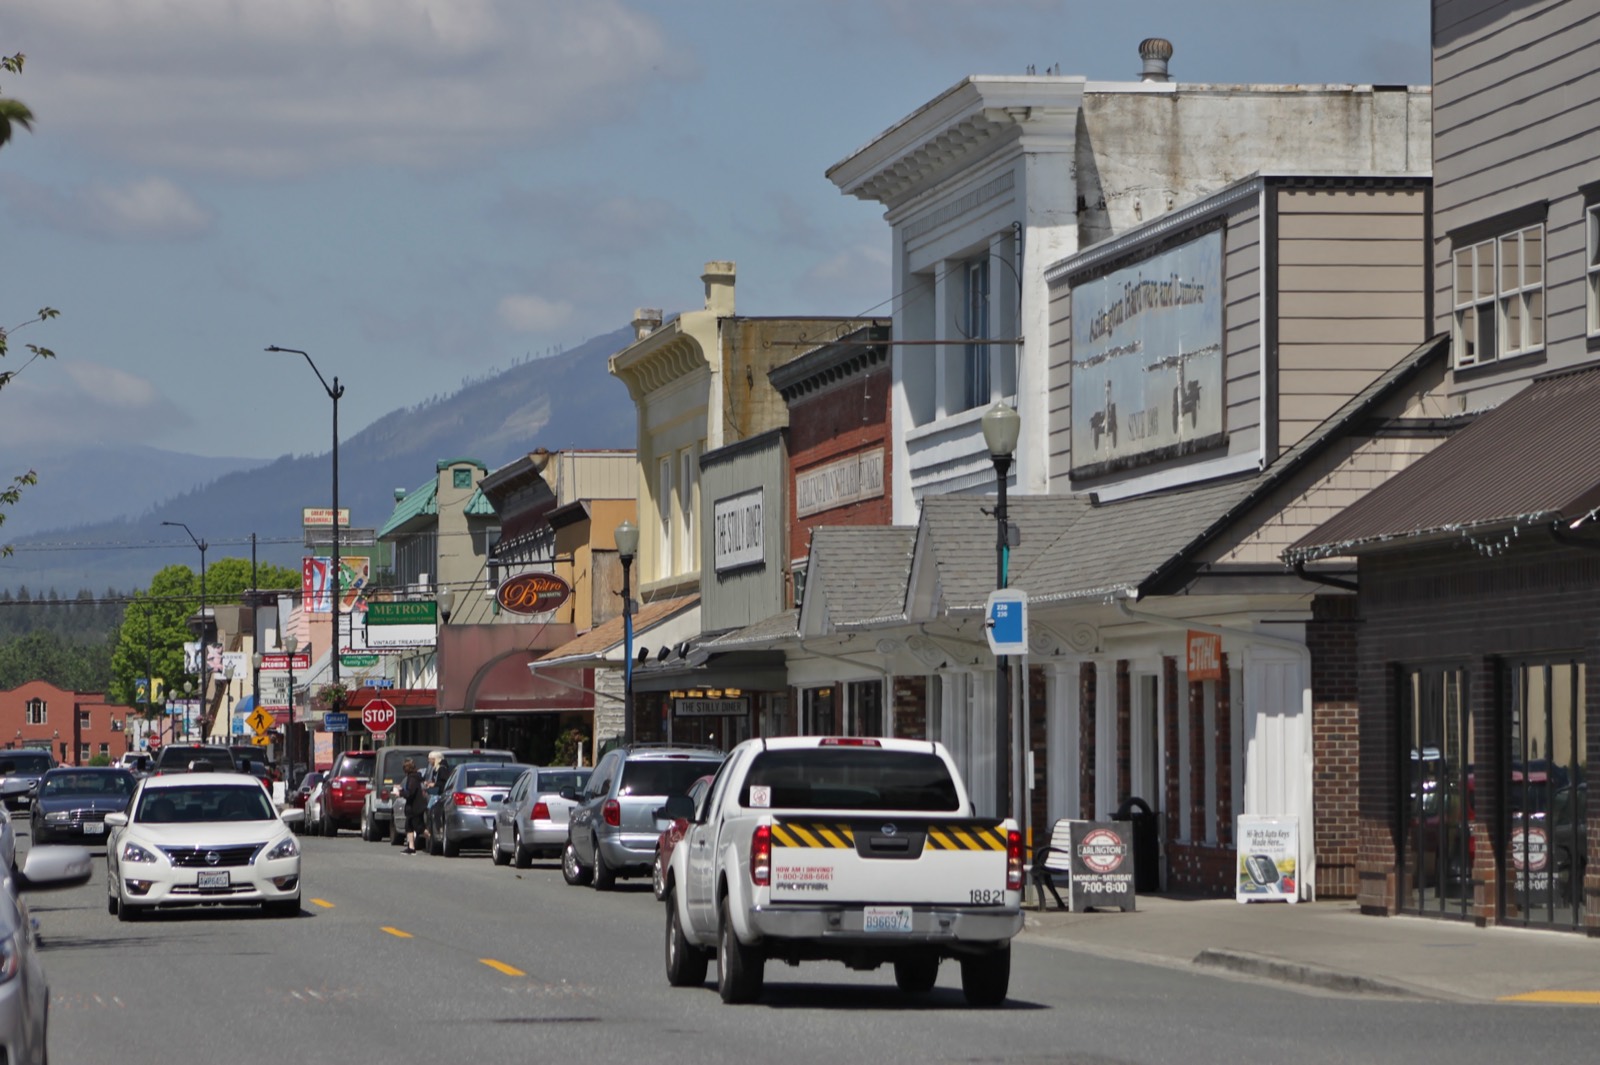
Photo: SounderBruce, CC BY-SA 4.0 (resized)
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Housing ranges from early-1900s homes in Old Town to 1990s and 2000s subdivisions such as Gleneagle and the newer neighborhoods around Smokey Point, plus farmhouses and manufactured homes on acreage. Pre-approval letters are typically valid for a limited time because credit reports and documents expire. If your search in Arlington takes longer, we refresh your documents and reissue the letter.
If the first review shows you are not quite ready, we will tell you what would help, whether that is paying down a balance, documenting income differently or saving a bit more for closing costs, and you can come back when the timing is right.
Home Right Lending works with borrowers throughout Arlington, including Kent Prairie, Arlington Heights, Bryant and Old Town Arlington, and across the north Snohomish County area. Arlington is about thirty-five to forty minutes from our Mill Creek office, and most of the loan process can be handled by phone and online.
If you are considering mortgage pre-approval in Arlington, call Home Right Lending at (425) 642-4477 or request a quote with the form on this page. Our Mill Creek office is open Monday through Friday, 9am to 5pm. Company NMLS 2362313. Equal Housing Opportunity.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Home Loan Pre-Approval · All loan options · Mortgage rates
Timing depends mostly on how quickly your documents arrive. A complete file with standard income moves fastest, while self-employment or other complex income takes longer to review.
A pre-approval requires a credit inquiry, which can have a small, temporary effect on your score. Credit scoring models generally treat multiple mortgage inquiries within a short shopping window as a single inquiry.
No. A pre-approval is based on the information reviewed at that time. Final approval is subject to underwriting, a satisfactory appraisal, title review and verification that your income, assets and credit have not changed.