
Stanwood is in the northwest corner of Snohomish County near the mouth of the Stillaguamish River, about forty-five minutes from our Mill Creek office, and it is the gateway to Camano Island. The town grew from two separate downtowns, and it is surrounded by farmland, lakes and saltwater shoreline. Before you tour homes in Stanwood, it helps to know your price range and your likely monthly payment. Home Right Lending offers home loan pre-approval that looks at your full financial picture and matches it to the loan programs you may be eligible for.
Call Home Right Lending at (425) 642-4477 about mortgage pre-approval in Stanwood.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Properties around Stanwood range from in-town subdivisions to farms, lake homes and manufactured homes on land, so the property type often decides which loan programs are available. Long-held homes can carry significant equity, and some rural addresses may fall within USDA-eligible areas depending on the current map. The process usually takes three steps: you apply online or by phone, you send income and asset documents, and we review everything and discuss the results with you. If something in the file needs attention, such as a credit item or a gap in documentation, you learn about it before you are under contract.
REQUEST A FREE CONSULTATION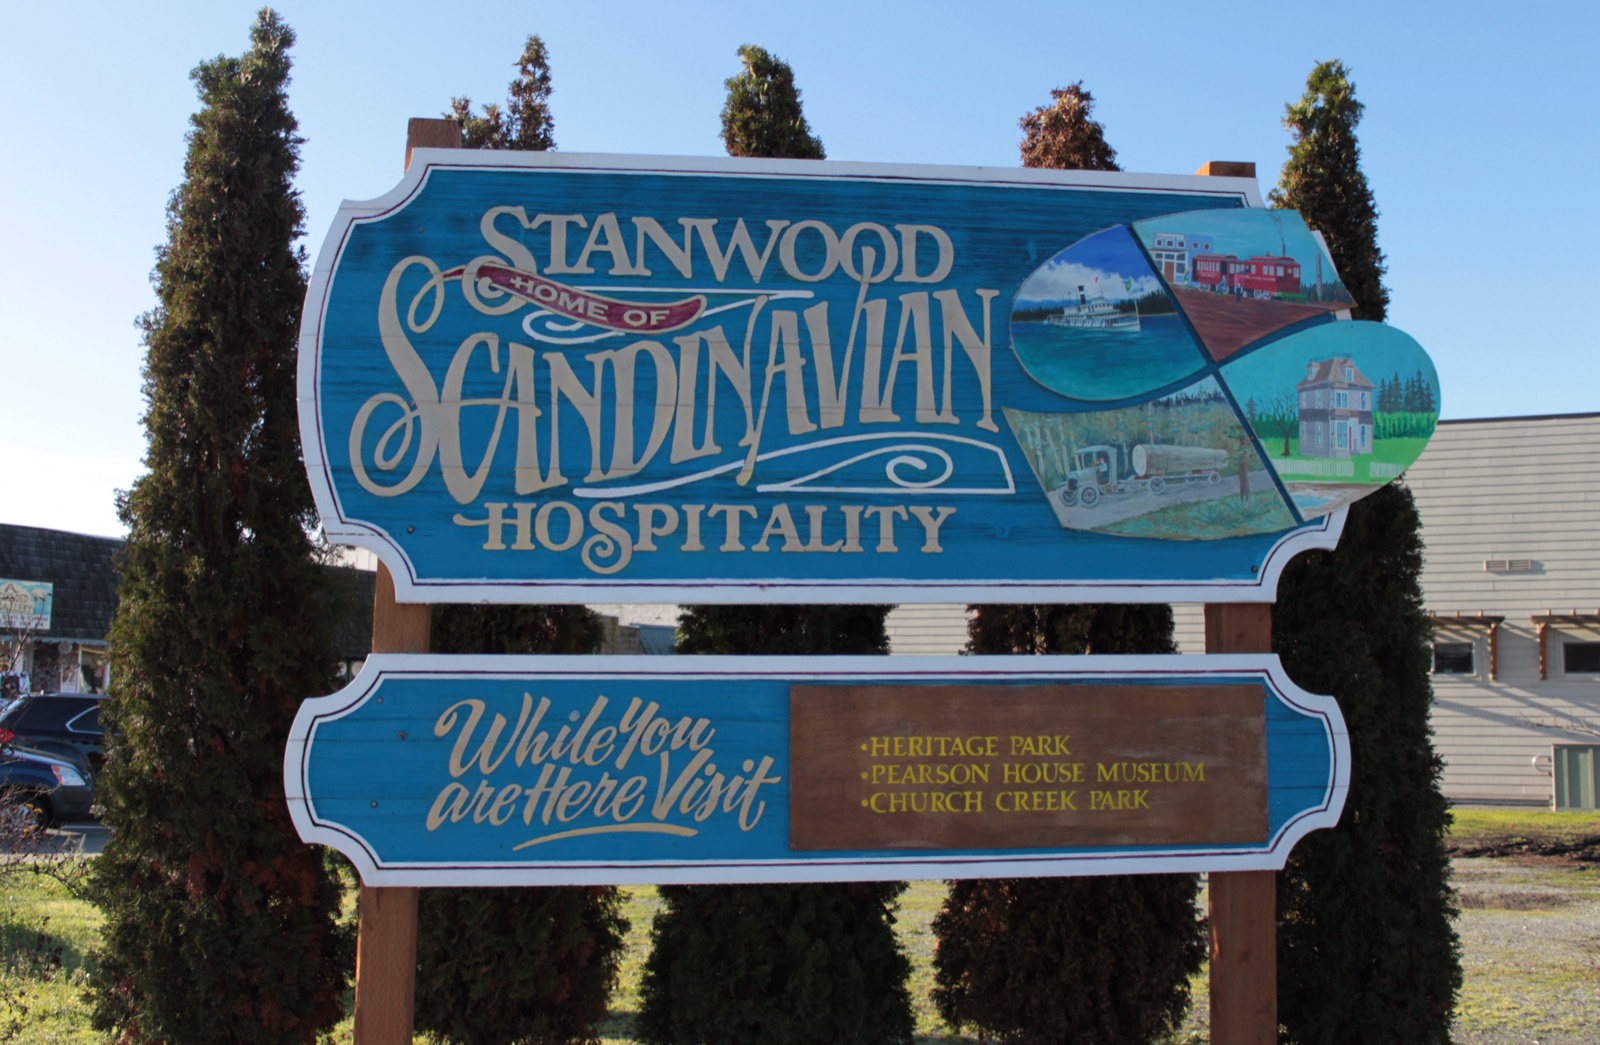
Photo: SounderBruce, CC BY-SA 2.0 (resized)
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Housing includes older homes in the East Stanwood and West Stanwood downtowns, newer subdivisions around Cedarhome and Church Creek, and rural and lake properties toward Warm Beach and Lake Goodwin. Once you are pre-approved, we can update the letter for specific offers so the amount matches what you are bidding on a home in Stanwood. When your offer is accepted, the file moves straight into processing because most of the documents are already in hand.
If the first review shows you are not quite ready, we will tell you what would help, whether that is paying down a balance, documenting income differently or saving a bit more for closing costs, and you can come back when the timing is right.
Home Right Lending works with borrowers throughout Stanwood, including West Stanwood, Cedarhome, Church Creek and Warm Beach, and across the Stanwood area. Stanwood is about forty-five minutes from our Mill Creek office, and the full loan process can be handled by phone and online.
Looking into mortgage pre-approval in Stanwood? Call (425) 642-4477 or apply online to get started, and a loan officer will review your situation and explain your options in plain language. Home Right Lending, NMLS 2362313. All loans are subject to credit approval and program guidelines.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Home Loan Pre-Approval · All loan options · Mortgage rates
A pre-approval requires a credit inquiry, which can have a small, temporary effect on your score. Credit scoring models generally treat multiple mortgage inquiries within a short shopping window as a single inquiry.
No. A pre-approval is based on the information reviewed at that time. Final approval is subject to underwriting, a satisfactory appraisal, title review and verification that your income, assets and credit have not changed.
Typically recent pay stubs, the last two years of W-2s or tax returns, recent bank statements and a photo ID. Self-employed borrowers should expect to provide business returns or, for certain programs, bank statements.