
Lake Stevens wraps around the largest natural lake in Snohomish County, east of Everett across the Highway 2 trestle and about twenty-five minutes from our Mill Creek office. The city has grown quickly, and newer subdivisions now surround the older lake cabins and waterfront homes. VA loans are a benefit earned through military service, backed by the Department of Veterans Affairs and available to eligible veterans, active-duty service members and some surviving spouses. Home Right Lending helps eligible borrowers in Lake Stevens use that benefit to buy or refinance a home.
Call Home Right Lending at (425) 642-4477 about a VA loan in Lake Stevens.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Much of the housing is recent construction in neighborhoods with homeowners associations, so association dues and, for brand-new homes, builder timelines and rate-lock length factor into financing. Waterfront and lake-view homes are a separate market and are appraised against a much smaller set of comparable sales. The first step is your Certificate of Eligibility, which confirms your entitlement, and we can help you request it. From there we review income, credit and residual income, the VA's measure of what is left each month after major expenses.
REQUEST A FREE CONSULTATION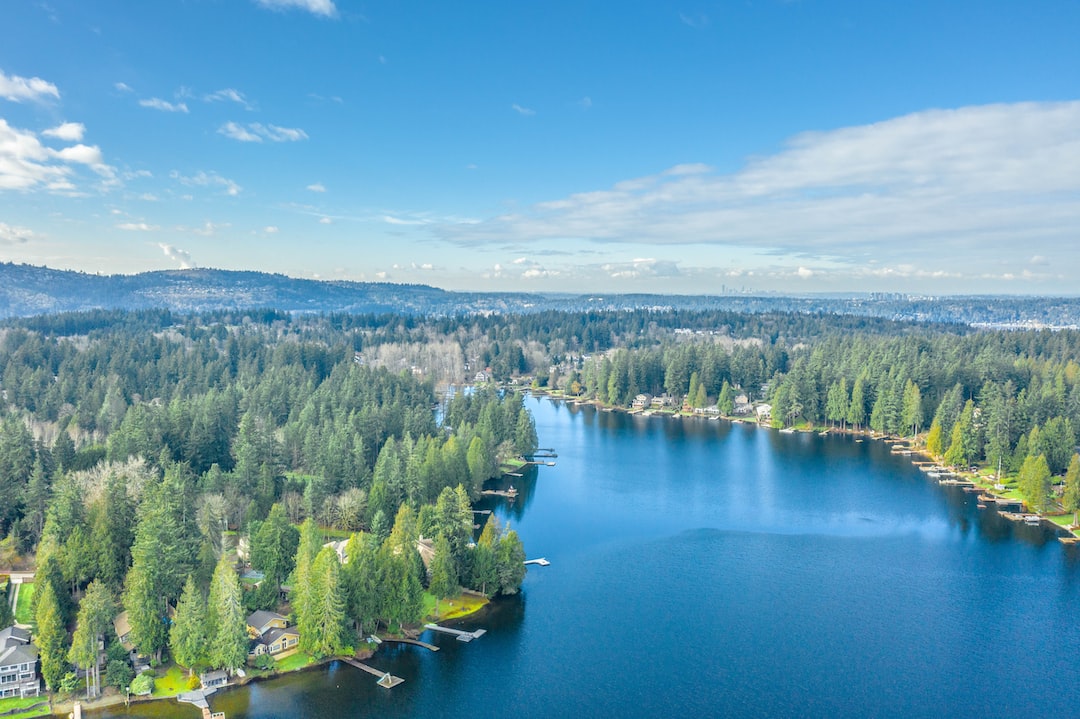
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Housing includes 1970s and 1980s homes near the lake, large subdivisions from the 2000s onward around Frontier Village, Soper Hill and Cavelero, and waterfront properties on the lake itself. We manage the VA appraisal, underwriting and closing timeline and keep you and your agent informed throughout. Most purchases take about 30 to 45 days, depending on the appraisal and the transaction.
Homeowners in Lake Stevens who already have a VA loan may qualify for the Interest Rate Reduction Refinance Loan, often called a VA streamline, or for a VA cash-out refinance. We will review whether either one offers a real benefit.
Whether the property is in or near Cavelero, Lundeen Park, Hartford or Downtown Lake Stevens, or elsewhere in Lake Stevens, the process is the same and we explain each step. Lake Stevens is about twenty-five minutes from our Mill Creek office.
If you are considering a VA loan in Lake Stevens, call Home Right Lending at (425) 642-4477 or request a quote with the form on this page. Our Mill Creek office is open Monday through Friday, 9am to 5pm. Company NMLS 2362313. Equal Housing Opportunity.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: VA Loans · All loan options · Mortgage rates
Eligibility is based on length and character of service and covers many veterans, active-duty service members, National Guard and Reserve members and certain surviving spouses. The VA confirms eligibility with a Certificate of Eligibility, which we can help you obtain.
Eligible borrowers with full entitlement can often buy with no down payment, as long as the home appraises for the purchase price and they qualify with the lender. Borrowers with partial entitlement may need a down payment on higher loan amounts.
It is a one-time fee paid to the VA that helps fund the program, and it can usually be financed into the loan. The percentage varies with down payment and prior use, and some borrowers, including veterans receiving VA disability compensation, are exempt.