
Brier is a small residential city in south Snohomish County, set between Mountlake Terrace, Lynnwood and Bothell and roughly twenty minutes from our Mill Creek office. It is known for large lots and a semi-rural feel, with very little commercial development inside the city limits. Refinancing replaces your current mortgage with a new one, either to change the rate or term or to take cash out of your equity. Home Right Lending helps homeowners in Brier compare refinance options across multiple wholesale lenders and decide whether the numbers make sense.
Call Home Right Lending at (425) 642-4477 about a mortgage refinance in Brier.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Because lots in Brier are larger than in neighboring cities, a purchase can reach the point where a jumbo or high-balance loan is needed, and long-held homes can carry significant equity. Some properties have detached shops, accessory buildings or room for horses, which appraisers treat differently than a standard suburban lot. Refinancing can restart the clock on your loan, which may lower the payment while increasing the total interest paid over time. We show you options with different terms so you can weigh the monthly payment against the long-run cost.
REQUEST A FREE CONSULTATION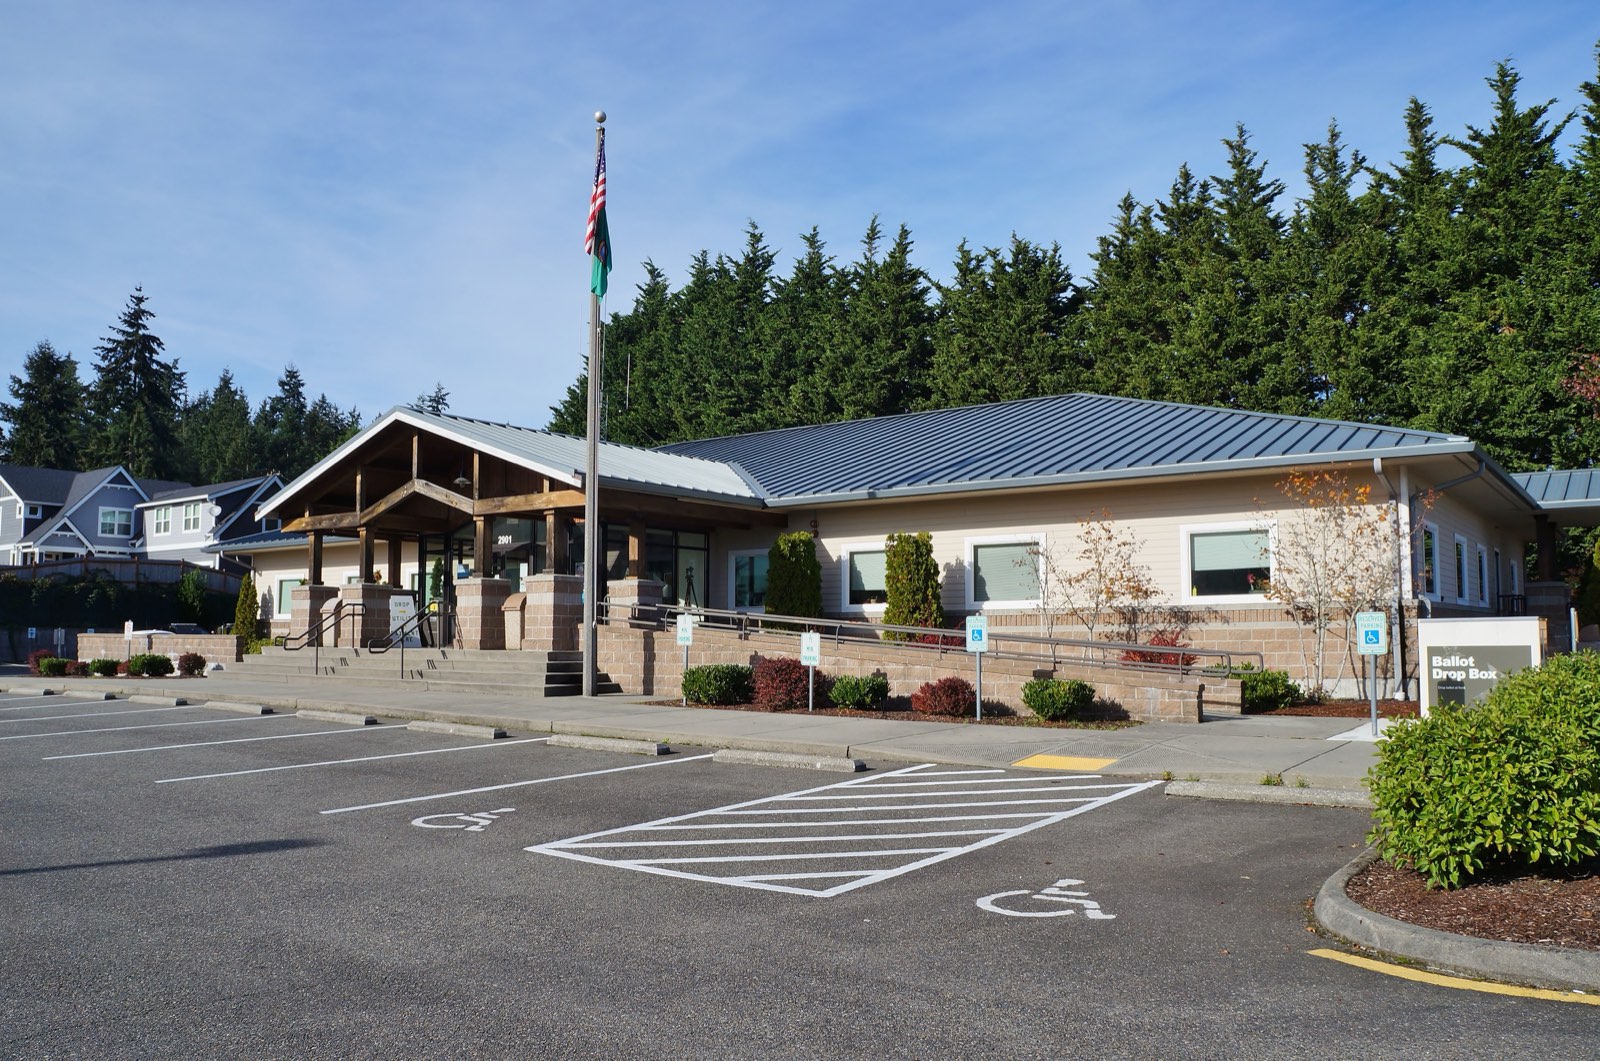
Photo: SounderBruce, CC BY-SA 4.0 (resized)
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Most homes are detached houses from the 1960s through the 1990s on large lots, with some newer custom construction mixed in. The process resembles a purchase loan: application, income and asset documents, an appraisal in most cases, underwriting and closing. On a primary residence, federal law gives you a three-day right to cancel after signing before the loan funds.
We do not quote rates on a web page because they change daily and depend on your credit, equity and loan type. Ask us for a written Loan Estimate for your Brier refinance and compare it with any other offer.
Our service area covers all of Brier, from Locust Way, Brier Park, Brierwood and Brier Road to the rest of the south Snohomish County area. Brier is roughly twenty minutes from our Mill Creek office.
Looking into a mortgage refinance in Brier? Call (425) 642-4477 or apply online to get started, and a loan officer will review your situation and explain your options in plain language. Home Right Lending, NMLS 2362313. All loans are subject to credit approval and program guidelines.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Mortgage Refinance · All loan options · Mortgage rates
It can make sense when the long-term benefit outweighs the closing costs, for example by lowering your rate, shortening your term, removing mortgage insurance or accessing equity for a specific need. We calculate the break-even point so you can decide.
A rate-and-term refinance changes your rate or loan term without taking significant cash out. A cash-out refinance increases the loan balance and pays you the difference, and it usually has stricter loan-to-value limits and different pricing.
Refinancing involves closing costs such as lender fees, appraisal, title and escrow charges. The amount depends on the loan size, the program and the lender, and it is itemized on your Loan Estimate.