
Monroe sits where Highway 2 and Highway 522 meet in the Skykomish River valley, roughly twenty-five to thirty minutes east of our Mill Creek office. It is the largest town in the Sky Valley and home to the Evergreen State Fairgrounds, with in-town neighborhoods surrounded by farmland and wooded acreage. Manufactured homes are part of the housing supply around Monroe, and they can be financed with many of the same programs as site-built homes when the home and land meet certain requirements. Home Right Lending helps you find out early whether a property qualifies.
Call Home Right Lending at (425) 642-4477 about a manufactured home loan in Monroe.
REQUEST A FREE CONSULTATION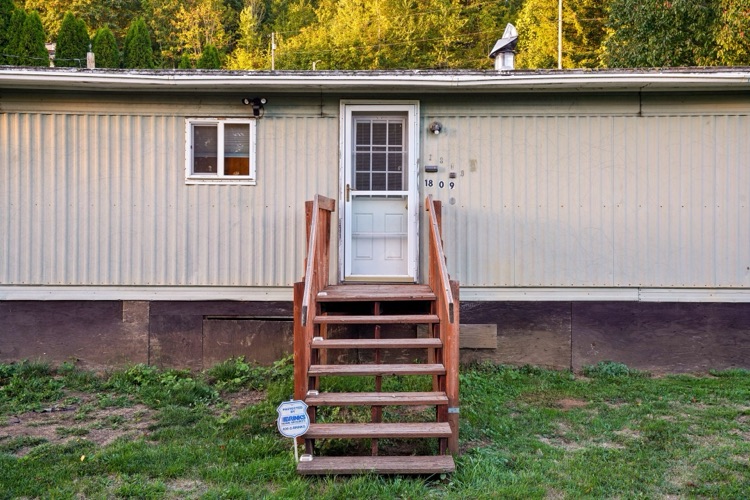
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Buyers here choose between subdivisions in town and rural properties outside it, and the two are financed differently: acreage often brings wells, septic systems and outbuildings, and manufactured homes need to meet foundation and title requirements. Some addresses outside the city may fall within USDA-eligible areas, which depends on the current eligibility map. In Washington, a manufactured home is typically financed as real estate once its vehicle title has been eliminated and the home is legally joined to the land. If that step has not been completed, it usually can be handled during the transaction with the title company.
REQUEST A FREE CONSULTATION
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Housing includes older homes near downtown, 1990s and 2000s subdivisions in Fryelands and around Lake Tye, and acreage along Chain Lake Road and Woods Creek. FHA and VA appraisals often call for a foundation certification from a licensed engineer. We tell you which reports your Monroe purchase is likely to need so they can be ordered early and the closing date stays on track.
Homeowners who already own a manufactured home on their own land in Monroe may be able to refinance, either to change terms or to access equity, as long as the home meets the lender's requirements.
Home Right Lending works with borrowers throughout Monroe, including Woods Creek, Tualco Valley, Downtown Monroe and Fryelands, and across the Sky Valley. Monroe is roughly twenty-five to thirty minutes from our Mill Creek office.
If you are considering a manufactured home loan in Monroe, call Home Right Lending at (425) 642-4477 or request a quote with the form on this page. Our Mill Creek office is open Monday through Friday, 9am to 5pm. Company NMLS 2362313. Equal Housing Opportunity.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Manufactured Home Loans · All loan options · Mortgage rates
FHA and VA loans typically require an engineer's certification that the foundation meets program standards, and some conventional lenders ask for one too. We let you know which reports apply to your loan.
Often, yes, if the home was built after June 15, 1976, is on a permanent foundation, is titled as real property and sits on land you own. FHA, VA, USDA and conventional programs each have their own additional requirements.
Homes on leased land generally do not qualify for standard mortgage programs and are financed with personal property loans instead. Fewer lenders offer them, and terms differ from a traditional mortgage.