
Granite Falls is a small city in the Cascade foothills at the start of the Mountain Loop Highway, about forty minutes northeast of our Mill Creek office. Its housing combines a compact downtown, a ring of newer subdivisions and wooded rural properties beyond the city limits. You do not always need 20% down to buy a home in Granite Falls. Home Right Lending compares low down payment mortgages from multiple wholesale lenders, including FHA, conventional, VA and USDA programs, and shows eligible buyers what each would cost.
Call Home Right Lending at (425) 642-4477 about a low down payment mortgage in Granite Falls.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Rural and semi-rural properties are a large part of this market, so wells, septic systems, private roads and manufactured homes come up often, and each affects which loan programs fit. Some addresses in the area may qualify for USDA financing, depending on the current eligibility map and the program's income limits. A smaller down payment usually means mortgage insurance and a higher monthly payment than the same home with more money down. We lay out the payment at different down payment levels so you can choose what fits your budget.
REQUEST A FREE CONSULTATION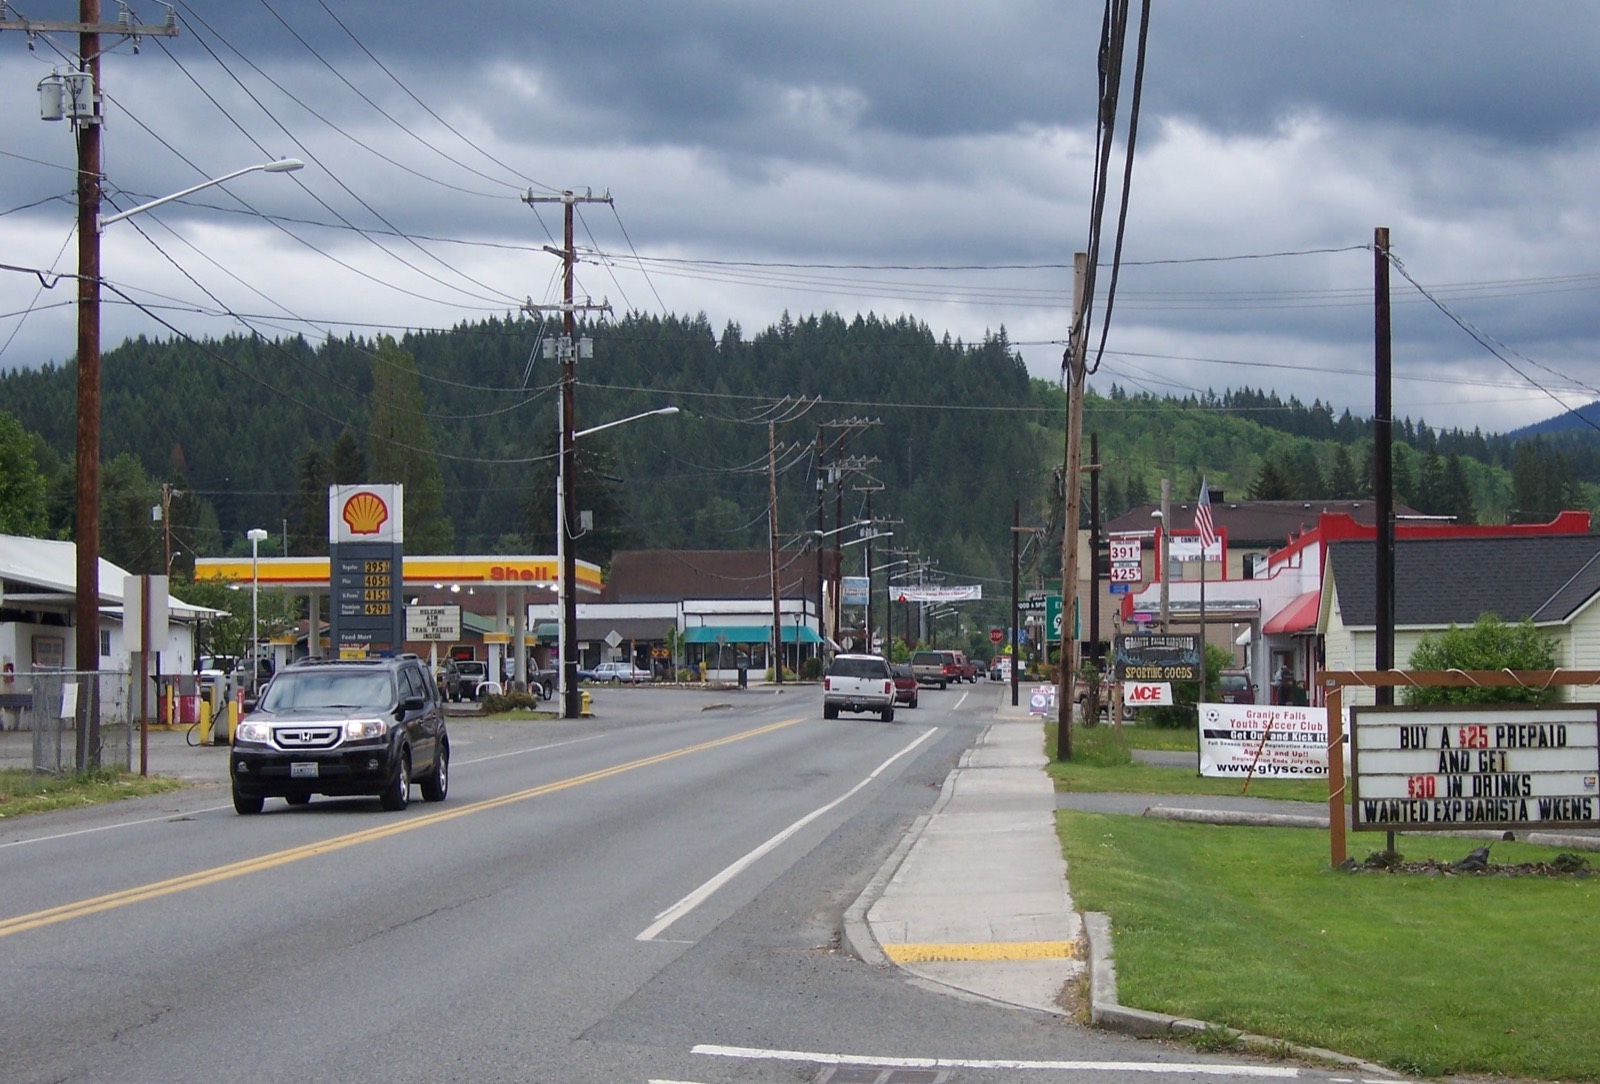
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Expect older homes near downtown, subdivisions built from the 1990s onward, and cabins, manufactured homes and custom homes on acreage along the Mountain Loop Highway and Menzel Lake Road. Even with a low down payment, you will need funds for closing costs and prepaid items. Seller credits, gift funds from eligible donors and down payment assistance may help cover them where program rules allow.
Low down payment loans are available on condos and townhomes as well as detached homes, though condos need to meet the program's project requirements. We check that early for any Granite Falls listing you are serious about.
Whether the property is in or near Robe Valley, Jordan Road, Lake Bosworth or Downtown Granite Falls, or elsewhere in Granite Falls, the process is the same and we explain each step. Granite Falls is about forty minutes from our Mill Creek office, and applications, documents and updates can all be handled by phone and online.
If you are considering a low down payment mortgage in Granite Falls, call Home Right Lending at (425) 642-4477 or request a quote with the form on this page. Our Mill Creek office is open Monday through Friday, 9am to 5pm. Company NMLS 2362313. Equal Housing Opportunity.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Low Down Payment Mortgages · All loan options · Mortgage rates
In many cases, yes. Assistance programs are often designed to pair with FHA, conventional, VA or USDA first mortgages for borrowers who meet income and other requirements. We check which combinations are allowed.
Sellers mainly care that the financing will close. A full pre-approval, a realistic timeline and a responsive lender carry a lot of weight, and we work with your agent to present your offer clearly.
Eligible veterans and service members may buy with no down payment on a VA loan, and USDA loans offer the same for eligible borrowers in eligible rural areas. Otherwise, FHA allows as little as 3.5% and some conventional programs 3% for qualifying buyers.