
Martha Lake is an unincorporated Snohomish County community between Lynnwood and Mill Creek, a short drive west of our office along 164th Street. It grew up around the lake of the same name and now mixes older lake-area homes with newer townhomes, condos and infill subdivisions near I-5. A pre-approval tells you, and the sellers you make offers to, how much home loan you may qualify for before you shop in Martha Lake. Home Right Lending reviews your credit, income and assets up front and issues a pre-approval letter based on documents instead of estimates.
Call Home Right Lending at (425) 642-4477 about mortgage pre-approval in Martha Lake.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
The 164th Street corridor has a large share of condos and townhomes, and condo financing depends on the association's budget, insurance and owner-occupancy as well as on the buyer. Quick access to I-5, I-405 and the Ash Way Park and Ride also makes Martha Lake a practical base for commuting in either direction. A pre-approval is not a final loan commitment. Final approval still depends on the appraisal, title work, the specific property and verification that your finances have not changed. What it does is remove most of the unknowns before you write an offer in Martha Lake.
REQUEST A FREE CONSULTATION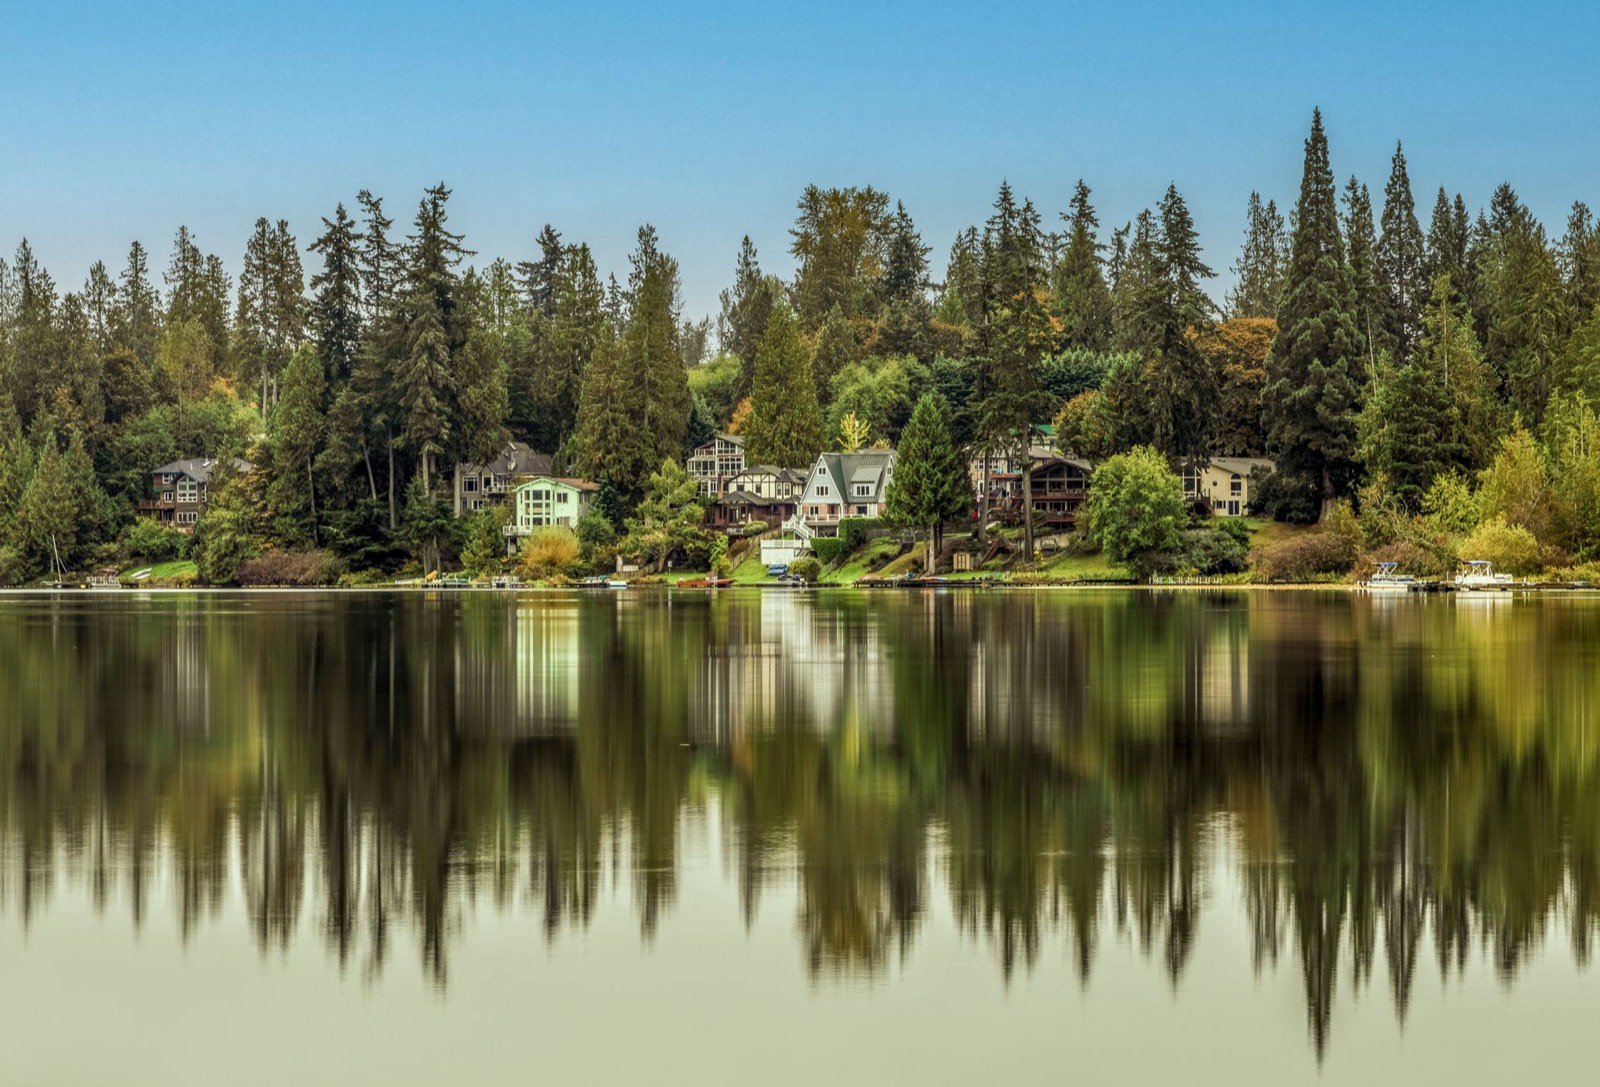
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
Housing includes 1960s through 1980s houses near the lake, newer two-story homes on smaller lots, and many townhome and condo communities along 164th Street and Ash Way. Self-employed borrowers, commission earners and borrowers with ITINs benefit from an early review, because their income takes longer to document. We identify which lenders and programs may fit before you start making offers in Martha Lake.
A pre-approval also lets you compare loan programs calmly, before a purchase deadline is running. We can show you how FHA, conventional, VA or other eligible options would change the down payment and monthly cost on a home in Martha Lake.
Home Right Lending works with borrowers throughout Martha Lake, including 164th Street SW, Ash Way, Larch Way and Filbert Road, and across the area between Lynnwood and Mill Creek. Martha Lake is about five to ten minutes from our Mill Creek office.
If you are considering mortgage pre-approval in Martha Lake, call Home Right Lending at (425) 642-4477 or request a quote with the form on this page. Our Mill Creek office is open Monday through Friday, 9am to 5pm. Company NMLS 2362313. Equal Housing Opportunity.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: Home Loan Pre-Approval · All loan options · Mortgage rates
A pre-approval requires a credit inquiry, which can have a small, temporary effect on your score. Credit scoring models generally treat multiple mortgage inquiries within a short shopping window as a single inquiry.
No. A pre-approval is based on the information reviewed at that time. Final approval is subject to underwriting, a satisfactory appraisal, title review and verification that your income, assets and credit have not changed.
Typically recent pay stubs, the last two years of W-2s or tax returns, recent bank statements and a photo ID. Self-employed borrowers should expect to provide business returns or, for certain programs, bank statements.