
Silver Firs is an unincorporated Snohomish County community just east of Mill Creek, reached from our office in a few minutes by 35th Avenue SE and Seattle Hill Road. It is made up almost entirely of planned subdivisions built from the 1990s onward, with sidewalks, neighborhood parks and homeowners associations. Home Right Lending arranges FHA purchase and refinance loans for Silver Firs homes through the wholesale lenders we work with. Because we are a broker, we can compare how different lenders price and underwrite the same FHA loan.
Call Home Right Lending at (425) 642-4477 about an FHA loan in Silver Firs.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Because nearly every Silver Firs home sits in a homeowners association, the dues are part of the monthly payment a lender qualifies you on. The homes are newer than much of the county, so appraisals tend to turn on recent comparable sales in the same subdivisions more than on repair items. An FHA loan requires an upfront mortgage insurance premium, which is usually financed into the loan, plus an annual premium paid monthly. In exchange, borrowers get a low minimum down payment and guidelines that allow higher debt-to-income ratios in some cases. The home must be your primary residence.
REQUEST A FREE CONSULTATION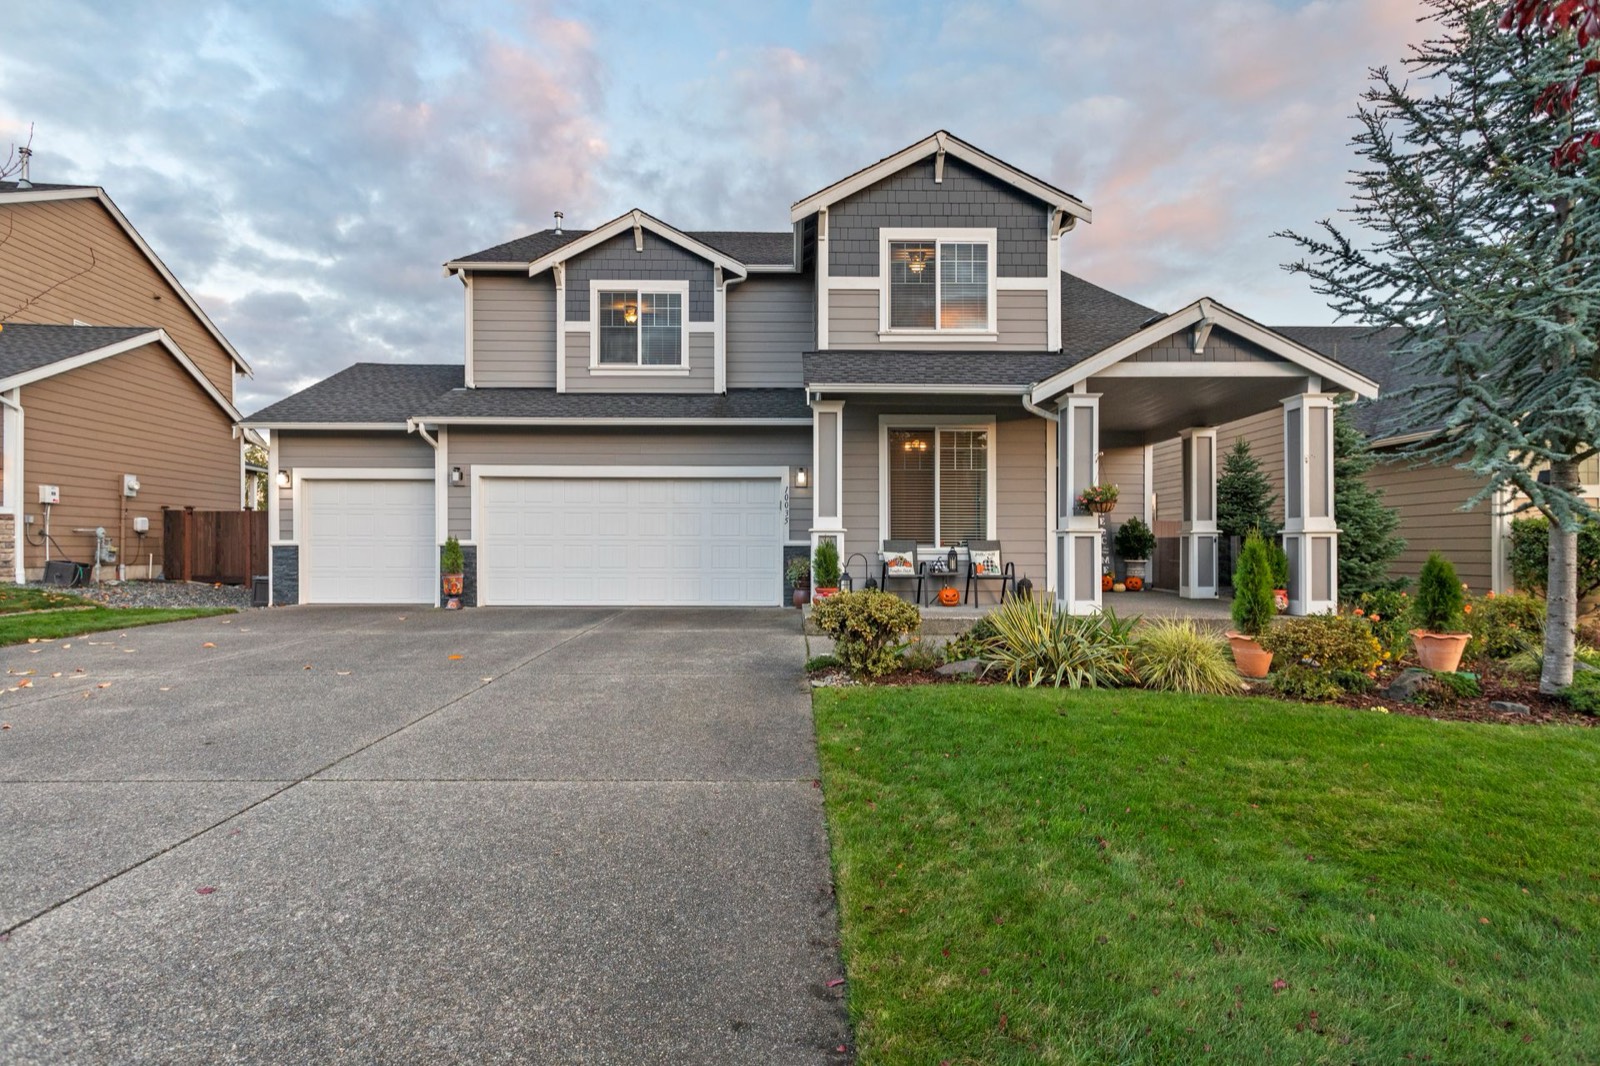
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
The housing stock is mostly two-story detached homes from the 1990s and 2000s, with some newer construction at the edges of the community. Down payment funds for an FHA loan can come from savings, a gift from an eligible donor or an approved assistance program. We document the source of funds carefully, since underwriters review bank statements for large or unexplained deposits.
Existing FHA borrowers in Silver Firs may be able to use the FHA Streamline Refinance, which has reduced documentation requirements for eligible loans. We can review whether it would produce a real benefit for you.
Home Right Lending works with borrowers throughout Silver Firs, including Thomas Lake, Seattle Hill Road, 35th Avenue SE and Snohomish Cascade, and across the Mill Creek and Silver Firs area. Silver Firs is roughly five to ten minutes from our Mill Creek office.
Thinking about an FHA loan in Silver Firs? Reach Home Right Lending at (425) 642-4477, apply online or use the form on this page, in English or Spanish. This is not a commitment to lend, and programs, terms and eligibility are subject to change. NMLS 2362313.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: FHA Loans · All loan options · Mortgage rates
FHA allows down payments as low as 3.5% of the purchase price for borrowers who meet the credit requirements. Borrowers with lower credit scores may need a larger down payment, and lenders can set their own additional standards.
Yes. FHA loans carry an upfront mortgage insurance premium and an annual premium paid as part of the monthly payment. How long the annual premium lasts depends on your down payment and loan term.
Yes, if the condominium project is FHA-approved or the unit qualifies for single-unit approval. We check the project's status early, because approval depends on the association's finances, insurance and owner-occupancy.