
Mountlake Terrace lies along I-5 at the southern edge of Snohomish County, about twenty minutes from our Mill Creek office. It was built largely as a postwar suburb, and its compact ramblers now sit alongside new apartments and townhomes near the light rail station and Town Center. For many buyers in Mountlake Terrace, an FHA loan is a practical way into a home: down payments can be as low as 3.5% for qualifying borrowers, and credit guidelines are more flexible than on many conventional loans. Home Right Lending can tell you whether FHA or another program is likely the better fit.
Call Home Right Lending at (425) 642-4477 about an FHA loan in Mountlake Terrace.
REQUEST A FREE CONSULTATION
We are a broker, so we compare loans from our wholesale lenders instead of offering one bank's menu.
Simple, honest updates from the first call to closing, so you always know what happens next.
Se habla español. We explain every step and every document in the language you prefer.
Self-employed, commission, multiple jobs or an ITIN: we look for the lender whose guidelines fit your file.
Your financial information is handled with care and shared only with the people working on your loan.
Meet us at 16300 Mill Creek Blvd #204 in Mill Creek, or handle everything by phone and online.
Smaller mid-century homes are a big part of the market here, and low down payment programs are often part of the conversation. Homes of this age can come with repair items, such as an older roof, dated wiring or a buried oil tank, that an FHA or VA appraiser may ask to have addressed. An FHA loan requires an upfront mortgage insurance premium, which is usually financed into the loan, plus an annual premium paid monthly. In exchange, borrowers get a low minimum down payment and guidelines that allow higher debt-to-income ratios in some cases. The home must be your primary residence.
REQUEST A FREE CONSULTATION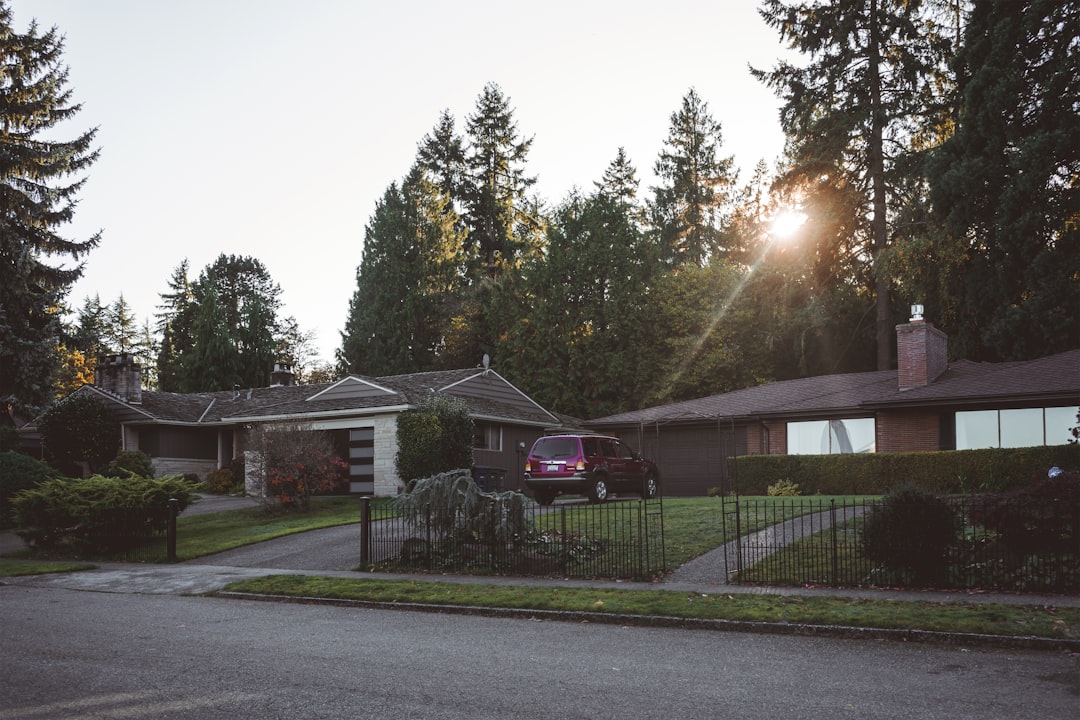
Tell us your goals. We look at your income, credit and down payment and explain which loans fit.
We review your documents and issue a pre-approval, so you can shop for a home with a real budget.
As a broker we shop your loan across our wholesale lenders. You pick the loan and lock your rate.
Appraisal, underwriting and final approval. Most purchase loans close in about 30 to 45 days.
The housing stock is dominated by 1950s and 1960s ramblers and split-levels, with newer townhomes and mixed-use buildings around Town Center and homes near Lake Ballinger. From application to closing, we manage the FHA case number, appraisal, underwriting conditions and final approval, and keep you informed at each step. Most purchases take about 30 to 45 days.
Existing FHA borrowers in Mountlake Terrace may be able to use the FHA Streamline Refinance, which has reduced documentation requirements for eligible loans. We can review whether it would produce a real benefit for you.
Whether the property is in or near Terrace Creek, Town Center, Lake Ballinger or Melody Hill, or elsewhere in Mountlake Terrace, the process is the same and we explain each step. Mountlake Terrace is about twenty minutes from our Mill Creek office by way of I-5.
If you are considering an FHA loan in Mountlake Terrace, call Home Right Lending at (425) 642-4477 or request a quote with the form on this page. Our Mill Creek office is open Monday through Friday, 9am to 5pm. Company NMLS 2362313. Equal Housing Opportunity.
REQUEST A FREE CONSULTATION
Learn more about the loan itself: FHA Loans · All loan options · Mortgage rates
No. Repeat buyers can use FHA financing as long as the home will be their primary residence and they meet the program's requirements. FHA is popular with first-time buyers because of the low down payment.
FHA allows down payments as low as 3.5% of the purchase price for borrowers who meet the credit requirements. Borrowers with lower credit scores may need a larger down payment, and lenders can set their own additional standards.
Yes. FHA loans carry an upfront mortgage insurance premium and an annual premium paid as part of the monthly payment. How long the annual premium lasts depends on your down payment and loan term.